Checking in with Paul Krugman’s 1996 pessimism regarding Taiwan
“The Tigers’ Problem Is Cyclical, for the Moment” (Wall Street Journal, November 5, 1996):
South Korea, Singapore, Hong Kong, Taiwan and the mini-tigers, Thailand, Malaysia, Indonesia and the Philippines, are facing flat domestic demand in key industrial countries, inventory corrections in the U.S., oversupply in the electronics industry, U.S. dollar strength and tight monetary conditions at home. These are cyclical problems that will reverse themselves soon enough. Down the line, the tigers may start facing structural constraints if they don’t educate their work force better, start investing more on R&D and become more receptive to skilled foreign workers. But for the time being, much of the present fear is misplaced.
Not everyone shares this view. Among the most famous critics of the “economic miracle” is U.S. economist Paul Krugman, who says that the region’s economies have prospered because of an exceptionally rapid expansion of inputs–labor and capital–rather than robust growth in output per unit of input, also known as productivity gains.
The Krugman thesis rests on the old-fashioned assumption that economic growth can be accounted for in terms of three distinct factors: labor, capital and technological progress. The third factor is considered independent of the other two; technological progress simply descends on an economy like “manna from heaven” instead of being the result of deliberate actions of profit-seeking agents. The thesis also holds that there is no tangible link between investment–in both human and physical capital–and technological progress. Underpinning much of Mr. Krugman’s claim that the input-driven expansion seen in East Asia is subject to constraints is the phenomenon of “diminishing returns.” The advantages derived from progress lessen with each passing day.
Imagine an investor who took Nobel laureate Krugman’s advice and shorted the following stocks in 1996: TSMC, Foxconn, ASUS (all were public companies at the time, ASUS having gone public exactly 30 years ago). How would such a Science-informed investor have done?
I asked ChatGPT to look into this.
Thirty years later, Taiwan’s economic performance presents a substantial challenge to the pessimistic interpretation of Paul Krugman’s 1994 argument about the Asian economic miracle. The interesting question isn’t simply whether Taiwan continued growing. It did. The more important question is whether Taiwan managed to sustain economic growth through productivity improvements rather than merely accumulating more capital and labor. And on that question, we now have nearly three decades of evidence.
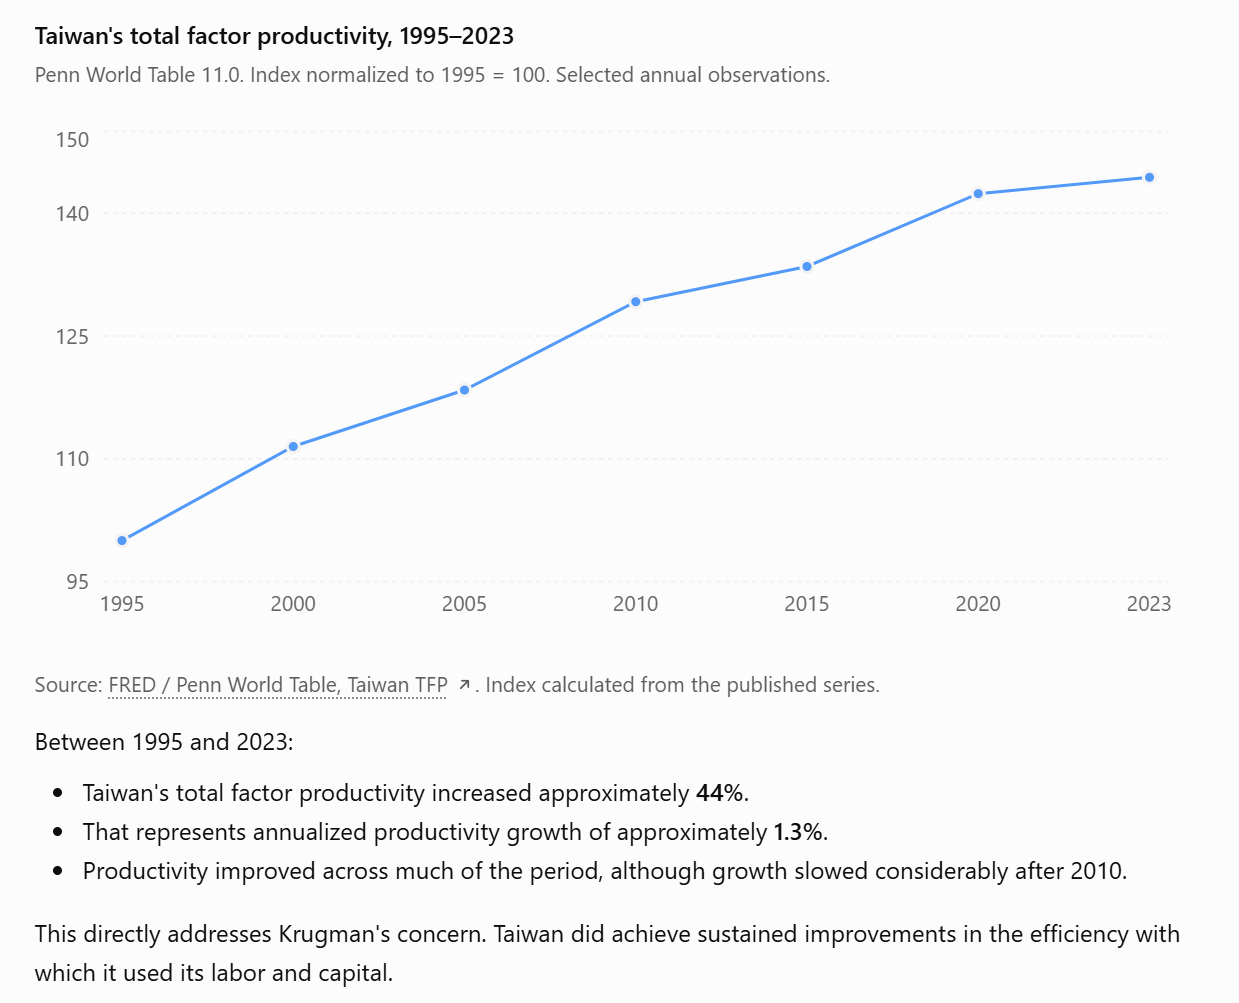
Between 1995 and 2025, Taiwan’s real GDP per worker increased by 160%, compared with 59% in the United States, 118% in South Korea, and just 18% in Japan. … In 1995, Taiwanese workers produced about 56% as much output per worker as Americans. By 2025, that figure had risen to approximately 92%. What does this say about Krugman’s prediction? It provides strong evidence against the idea that Taiwan’s growth would soon run into a severe productivity-related ceiling.
Taiwan sustained 3.24% annual growth in real output per worker for 30 years, during a period when the United States managed 1.56%.
The growth story is remarkable because we’re informed that importing humans from all of the world’s poorest, most violent, and most dysfunctional societies has been the basis for U.S. economic growth. Taiwan has had some temporary workers from functional societies, such as Thailand, but they weren’t invited to immigrate. Taiwan does not offer asylum. Taiwan has accepted no refugees during the 30 years covered. Taiwan will barely accept the Haitians and Somalis who built Boston and Minneapolis as visitors and certainly not as immigrants. While 25% of the world’s Mexicans live in the U.S., ChatGPT can’t find even one example of a Mexican emigrating to Taiwan.
What about the specific inspired-by-Krugman short seller? If he/she/ze/they (the trans have always been with us, even in 1996) had shorted $1,000 each of TSMC, Foxconn, and ASUS at the end of 1996, he/she/ze/they would currently be down $816,257:
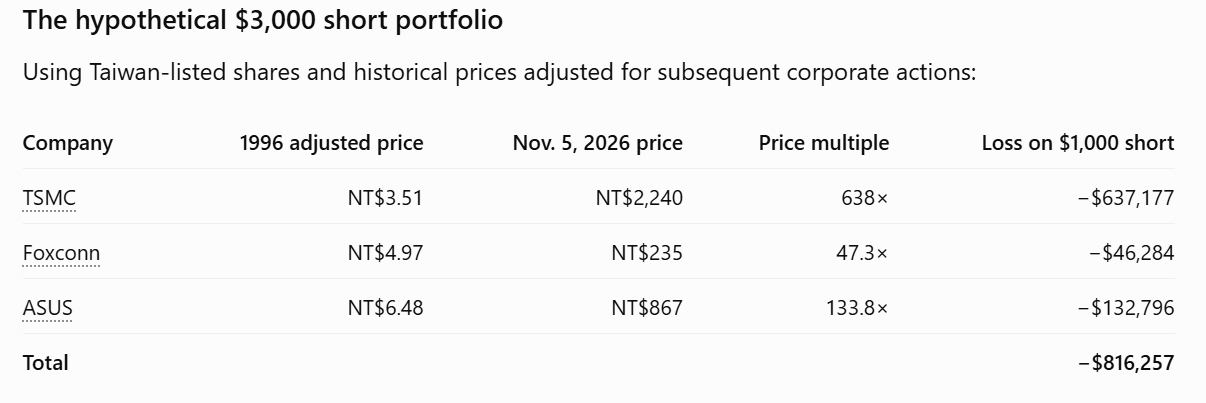
One tweak: “For an American investor, we should also account for the Taiwan dollar’s depreciation against the U.S. dollar.” The loss after currency adjustment would be only $681,185 on the $3,000 short. On the other hand, the loss is understated because ChatGPT thinks that it couldn’t fully account for stock dividends, ASUS’s Pegatron spinoff (2010), and the borrowing costs for the shares.
Asked to explain how Taiwan could have thrived with a workforce that grew older and almost no low-skill immigration, ChatGPT cites a Congressional Budget Office study from 2024 that predicted the Biden-Harris immigration surge would result in lower U.S. GDP per capita:
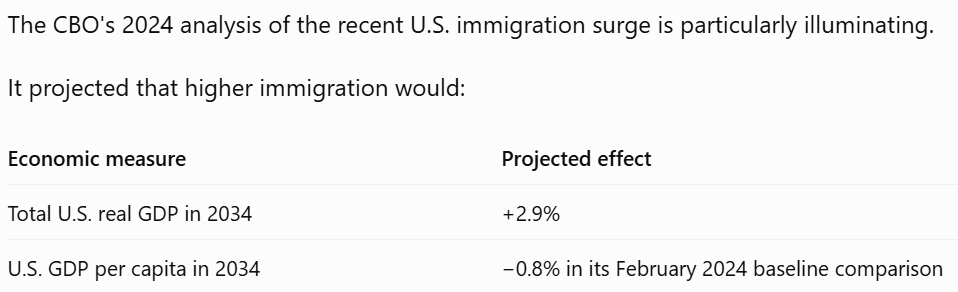
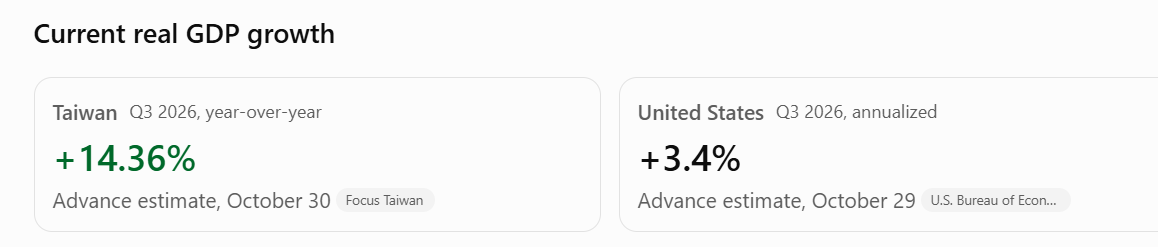
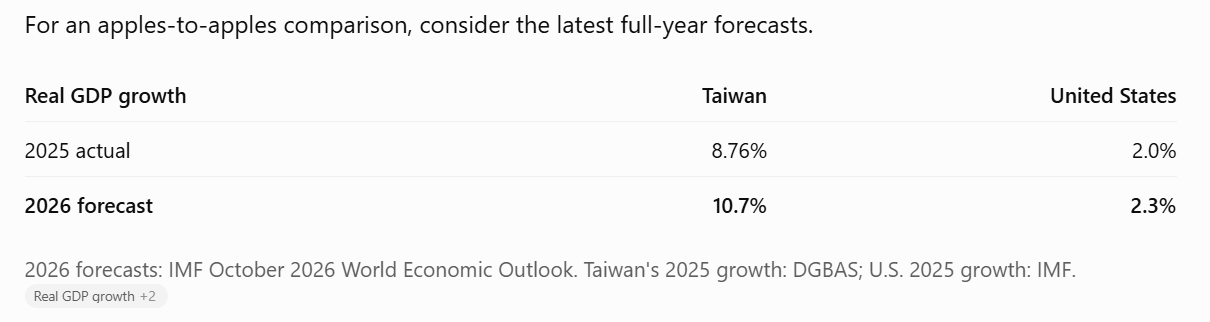
What about the strategy of importing welfare-dependent young people as a means of dealing with the challenge of providing for a growing number of welfare-dependent old people? That’s supposedly necessary to avoid economic decline due to an increasing median age. Over the 30 years covered by this analysis, Taiwan’s median age went from 29.8 to 45.7. The Taiwanese are growing much faster than we are right now, especially per capita, despite having a higher median age population (the U.S. is at 39.4 years). Here are the aggregate numbers (per-capita would make the U.S. look worse):
Related:
Full post, including comments